Purchasing
Purchase orders, goods receipts and bills are not the same
Keep commitments, received inventory and supplier liabilities separate for cleaner purchasing and accounting.
· 6 minute read
Three different events
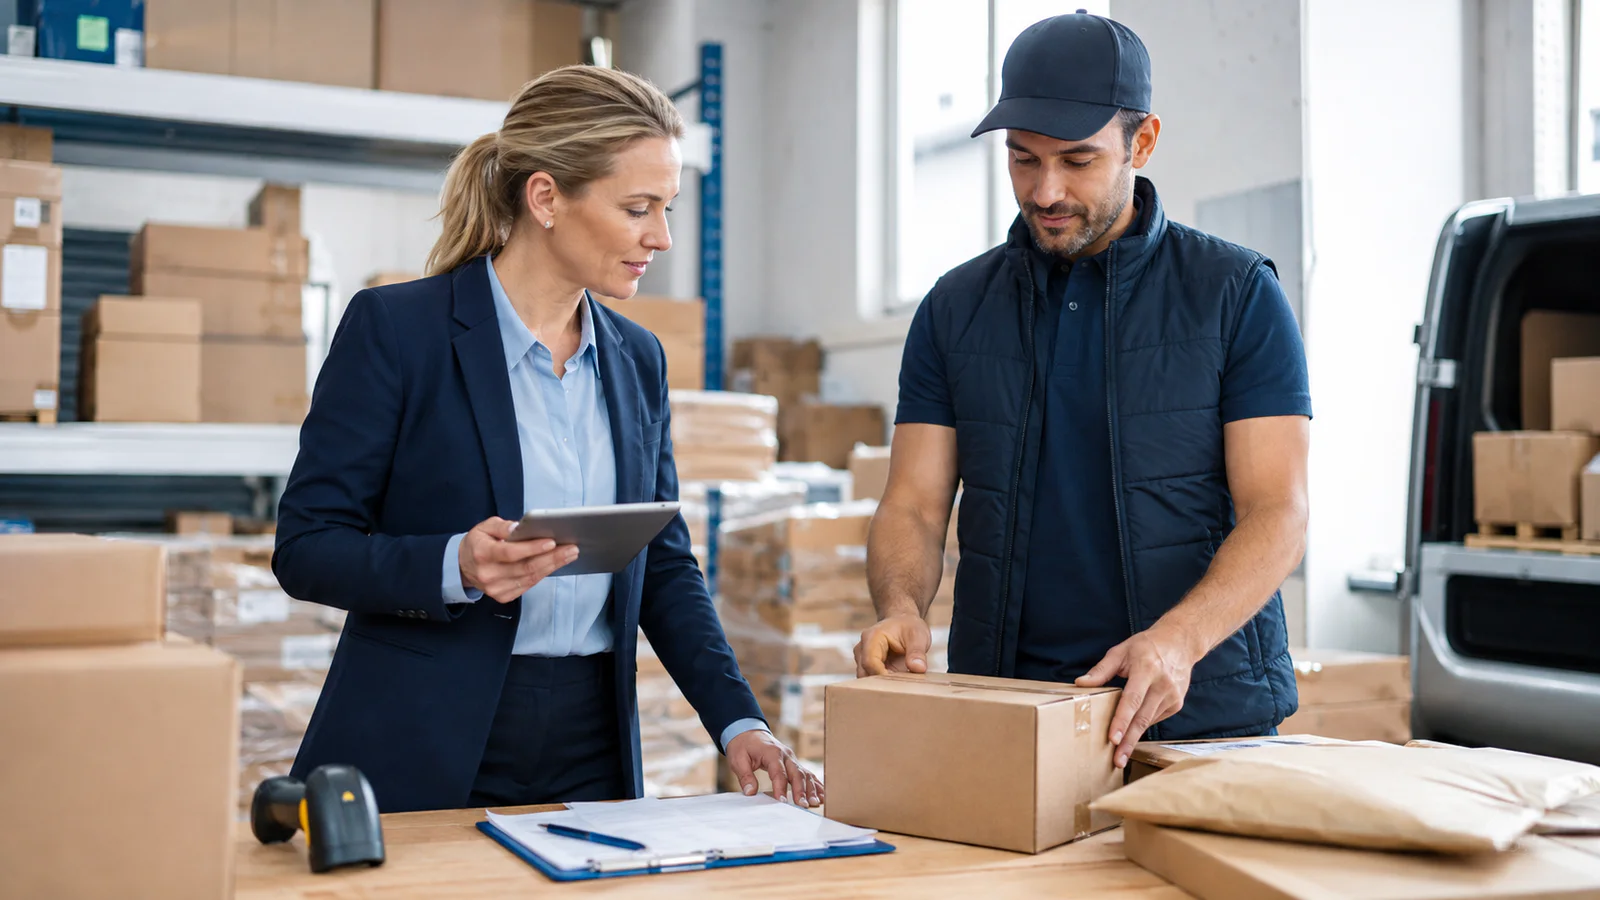
A purchase order states what you intend to buy. A goods receipt records what physically arrived. A supplier bill establishes what the supplier is charging and when it is due.
Combining them can be convenient for a simple immediate purchase, but the records must remain conceptually separate when deliveries are partial or prices change.
- ✓A purchase order is not automatically Accounts Payable
- ✓Receiving should update quantities actually accepted
- ✓Landed costs belong in inventory cost when appropriate
- ✓Payments reduce the supplier balance after billing
Define success before changing purchase-to-pay control
A credible purchase-to-pay control project starts with an operational definition of success. It should describe what becomes faster, safer or easier to understand for the buyer, receiving staff and accounts payable. Feature names alone are not enough because two systems can advertise the same capability while handling exceptions very differently. Document the current process, the people involved, the approvals that matter and the evidence needed after a transaction is complete. That baseline makes later evaluation objective and prevents the project from drifting toward whichever demonstration looks most impressive.
Map the information that must stay connected: purchase orders, deliveries, accepted quantities, landed costs, supplier bills, credits and payments. Decide which record is authoritative, who may create or correct it and what should happen when information is incomplete. The most useful design avoids duplicate entry and preserves the relationship between an operational event and its financial or inventory result. The central risk is using one document to represent a commitment, a physical delivery and a financial liability. Treat that risk as a testable requirement rather than a concern to discuss after implementation.
Model the real working day
Walk through ordering, receiving, checking discrepancies, approving bills and paying suppliers. Include quiet routines and high-pressure moments: the opening rush, a customer correction, a partial delivery, an interrupted connection and the end-of-day handover. A system is dependable when normal work is obvious and unusual work has a controlled path. If staff must remember hidden rules or maintain a parallel spreadsheet, the process is not truly integrated even when the software technically contains the data.
Order ten units, receive eight with one damaged, and receive a bill for ten at a changed price. The workflow should preserve every difference instead of silently forcing the documents to agree. Observe the number of decisions, screens and manual calculations involved. Ask what the next employee or manager will see and whether the final reports explain the outcome. A realistic scenario often reveals more than a long requirements document because it exposes timing, ownership and error recovery together.
Build controls into the workflow
Good control does not mean adding approval to every click. It means placing proportionate safeguards where a mistake would affect cash, inventory, customer obligations or the books. Required fields, sensible defaults, role permissions, immutable posted records and reason codes for adjustments are usually more valuable than complicated chains of approval. The interface should explain what is missing before submission and should never expose a technical database error to an employee or customer.
Separate drafts from posted events. A draft may be edited because it represents intent; a posted sale, receipt, payment or journal entry should be corrected through a visible reversal or adjustment. This preserves the history needed for investigation and reporting. Give supervisors concise exception lists so they can focus on unusual activity instead of reviewing every normal transaction.
Prepare accurate data without importing disorder
Clean the essential data before migration. Standardize names, units, tax treatment, identifiers and opening balances, then remove obvious duplicates. Import a small sample first and verify it in the screens and reports where people will use it. A successful import is not merely a row count; relationships, totals and business meaning must survive. Keep the original source files and a dated reconciliation so the opening position can be explained later.
Avoid importing years of low-value detail simply because it exists. Active master records, open balances, current stock and legally required history usually deserve priority. Older information can remain in a controlled archive when the cost and risk of full migration exceed its operational value. The goal is a clean starting point, not a new home for every historic inconsistency.
Train by role and exception
Training should follow the work each role performs. Cashiers need speed, correction and handover practice; managers need approvals, exceptions and close procedures; owners need to understand the figures and alerts that require action. Short sessions using realistic data are more effective than a single tour of every menu. Give each role a concise checklist and confirm competence with a practical task.
Teach failure recovery as deliberately as the happy path. Staff should know what happens after a printer problem, incorrect quantity, duplicate attempt, connection loss or interrupted close. They also need to know when not to improvise. Clear recovery guidance protects both customer experience and data integrity, and it reduces support requests during the first weeks of use.
Measure adoption and operating quality
Review a small set of measures that reveal whether purchase-to-pay control is producing the intended result. Useful starting measures include supplier delivery accuracy, unbilled receipts, price and quantity variances, average supplier payment time. Establish the baseline before launch, define how often each measure is reviewed and name the person responsible for acting on it. A dashboard without ownership creates visibility but not improvement.
Combine numbers with structured feedback from the people doing the work. A slower step may indicate missing training, poor data or an unnecessary control rather than a software defect. Conversely, a fast workflow may hide weak audit evidence. Review both efficiency and correctness, and change one thing at a time so the effect can be understood.
Use a sustainable review rhythm
Use three-way comparison of order, receipt and bill with clear exceptions. Daily checks should be short and exception-focused; weekly reviews can address trends and unresolved items; month-end review should confirm that operational totals agree with the relevant balances. Record decisions and owners for follow-up. This rhythm prevents small discrepancies from becoming expensive investigations and keeps the system aligned with changing business practices.
Plan a review after the first week, first month and first quarter. Remove workarounds that appeared during launch, refine permissions and update training where repeated mistakes occur. New features should be introduced only when the existing process is stable and the benefit is clear. Sustainable improvement comes from disciplined, understandable changes—not from enabling every available option at once.
A practical decision standard
The final decision should be explainable in plain language: how the proposed approach improves daily work, protects the records, survives predictable disruption and supports management decisions. Confirm ownership of backups, exports and support. Verify the full cost, contractual term and exit path. When an external service is involved, identify exactly which information leaves the business and what local work remains possible during an outage.
For purchase-to-pay control, prefer the smallest design that completely handles the real workflow and its important exceptions. Simplicity is not the absence of control; it is a clear model with fewer unnecessary moving parts. When staff can complete their work confidently and an owner can trace the result from source activity to summary, the system is delivering durable business value.